Coffee market analysis for October 25, 2026: London Robusta continues to decline in the final session of the week, domestic prices retreat to around the VND 90,000 mark
Today is Sunday, so the London and New York exchanges are not trading. Therefore, the analysis for October 25 summarizes the final trading session of the week, which was Friday, October 23, on the two international exchanges, along with domestic green coffee prices surveyed on October 24. Both markets declined: London Robusta fell for the fourth consecutive session according to the price report on October 24, New York Arabica also reversed to decline, and domestic prices moved away from the VND 94,000 level recorded at the beginning of the week.
Note on timestamps in this article. The international prices cited are the closing prices from Friday, October 23, as published in the price report on October 24. Domestic prices are those surveyed on October 24. As there were no new trading sessions on the two exchanges on October 25, this article does not quote prices specifically for October 25.
1. London Robusta declines across all three contract months in the final session of the week
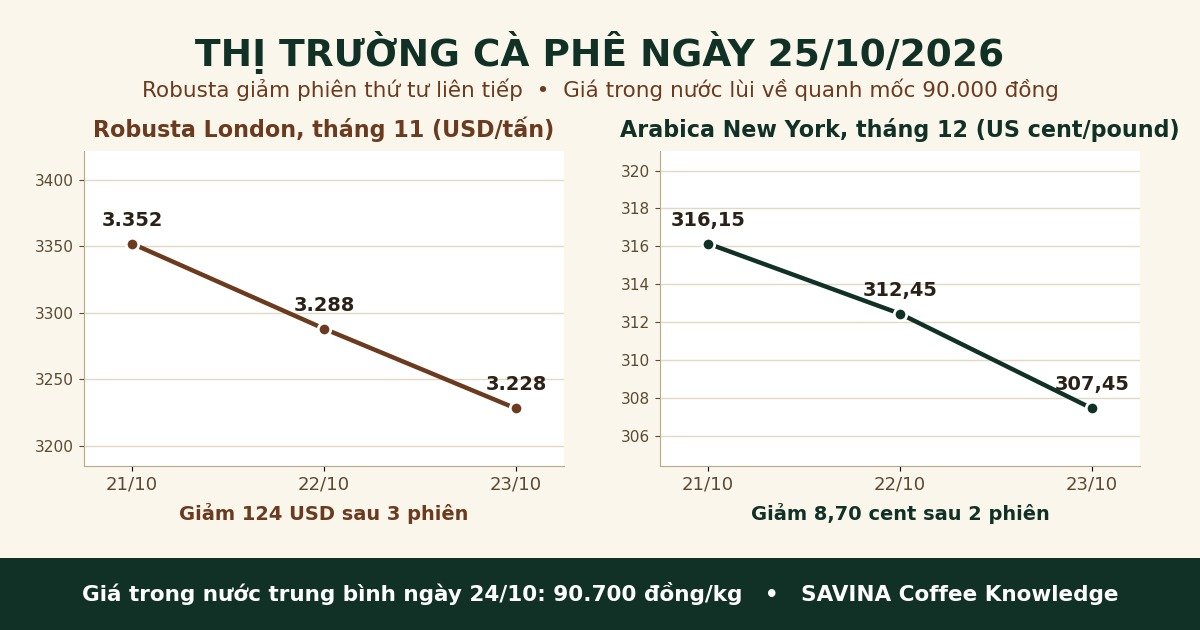
On ICE Futures Europe, the November 2026 Robusta contract closed the final session of the week at USD 3,228/tonne, down USD 60/tonne, equivalent to 1.82% compared to the previous session. The January 2027 contract closed at USD 3,242/tonne, down USD 59/tonne, equivalent to 1.79%. The March 2027 contract closed at USD 3,229/tonne, down USD 45/tonne, equivalent to 1.37%. The uniform decline across all three contract months indicates that correction pressure is not concentrated solely on near-term contracts.
| London Robusta Contracts | Closing Prices for the Final Session of the Week (USD/tonne) | Change from Previous Session |
| November 2026 | 3.228 | Down USD 60, equivalent to 1.82% |
| January 2027 | 3.242 | Down USD 59, equivalent to 1.79% |
| March 2027 | 3.229 | Down USD 45, equivalent to 1.37% |
Over the three sessions, the November contract fell by a total of USD 124, equivalent to 3.70%, from 3,352 to 3,228. The January contract fell by a total of USD 122, from 3,364 to 3,242. The price trended downward evenly across all three sessions without any intervening recovery session, indicating sustained selling pressure rather than an isolated volatile session.
2. New York Arabica reverses to decline after mid-week recovery
On ICE Futures US, the December 2026 Arabica contract closed the final session of the week at 307.45 US cents/pound, down 5.00 cents, equivalent to 1.60% compared to the previous session. The March 2027 contract closed at 293.40 US cents/pound, down 4.05 cents, equivalent to 1.36%. The May 2027 contract closed at 289.00 US cents/pound, down 3.45 cents, equivalent to 1.18%. Thus, Arabica reversed direction after the recovery noted in SAVINA's analysis on October 22, when the December contract was still at 316.15 US cents/pound.
| New York Arabica Contracts | Closing Prices for the Final Session of the Week (US cents/pound) | Change from Previous Session |
| December 2026 | 307,45 | Down 5.00 cents, equivalent to 1.60% |
| March 2027 | 293,40 | Down 4.05 cents, equivalent to 1.36% |
| May 2027 | 289,00 | Down 3.45 cents, equivalent to 1.18% |
From 316.15, the December contract fell a total of 8.70 cents, equivalent to 2.75%, over two sessions. This decline was smaller than that of Robusta during the same series of sessions, consistent with the inventory picture: Arabica remains partially supported by low inventories, while Robusta faces additional pressure from rising stockpiles.
3. Domestic prices fell across the board, with Đắk Nông maintaining the highest level
Green bean prices in the Central Highlands on October 24 decreased by VND 500–600/kg compared to the previous day across all four surveyed regions. Đắk Lắk and Gia Lai both dropped by VND 600, to VND 90,800/kg. Lâm Đồng fell by VND 600, to VND 90,200/kg, the lowest among the surveyed group. Đắk Nông decreased by VND 500, to VND 91,000/kg, remaining the region with the highest price. The average across the four regions stood at VND 90,700/kg.
| Region | Price on October 23 (VND/kg) | Price on October 24 (VND/kg) | Change |
| Đắk Lắk | 91.400 | 90.800 | Down VND 600 |
| Lâm Đồng | 90.800 | 90.200 | Down VND 600 |
| Gia Lai | 91.400 | 90.800 | Down VND 600 |
| Đắk Nông | 91.500 | 91.000 | Down VND 500 |
| Average of four regions | 91.275 | 90.700 | Down VND 575 |
The three-day sequence shows a steady decline in domestic prices: the four-region average fell from VND 91,700/kg on October 22 to VND 91,275/kg on October 23, and then to VND 90,700/kg on October 24, for a total drop of VND 1,000/kg. In Đắk Nông, the region with the highest prices, the decrease amounted to VND 3,000/kg from the VND 94,000/kg recorded on October 21, according to the price update on October 24. The VND 90,000/kg level is becoming a notable benchmark for the domestic market in the final sessions of October, as prices approach this threshold from above.
Actual purchase prices at individual dealers may vary depending on coffee quality, moisture content, impurity ratio, delivery method, and payment terms. Readers should compare the surveyed prices in this article with local dealer prices before making trading decisions.
4. Why did the market decline together in the final session of the week?
Profit-taking after the mid-October rally. According to Barchart analysis cited by the price report, the main pressure came from some long positions being closed out following the price surge in mid-October. When prices rise rapidly over a short period, selling pressure from profit-taking is sufficient to pull both exchanges down, even in the absence of any breakthrough new supply and demand information.
Diverging inventory trends on the two exchanges. Certified Arabica inventories at ICE fell further in the final session of the week, dropping to a five-week low of 227,978 bags. Previously, these inventories had increased by 4,847 bags on Wednesday to 239,748 bags, then decreased by 5,315 bags on Thursday and by another 6,455 bags on Friday. However, news that nearly 28,000 bags of Arabica are awaiting grading at ICE—the highest level in over a month—has led the market to expect inventories may rise again in the short term, and this expectation is strong enough to outweigh the signal from current low inventory levels. Conversely, Robusta inventories at ICE have risen sharply over the past six weeks, reaching 6,612 lots by the end of the week, the highest level in 13 months, creating direct downward pressure on Robusta prices.
New crop supply entering the market. Supply from Brazil's new harvest is gradually entering the market, while Vietnam has also begun its 2026/2027 coffee crop harvest. The domestic harvest is entering a more active phase, with the actual volume of goods brought to market increasing gradually, coinciding with international price corrections, which has made trading sentiment more cautious. This is also the context in which coffee cherry ripeness and post-harvest cherry sorting become critical for raw material quality, as the first batches of the harvest are the most susceptible to spoilage if processing is delayed.
The strengthening Brazilian real remains the remaining support for Arabica. According to the price report, the Brazilian real continues to strengthen due to internal political factors, and this factor is still supporting Arabica prices. Thanks to this support, Arabica's decline over the recent series of sessions was milder than Robusta's, although both faced profit-taking pressure.
5. Factors to monitor in the coming week
The first trading session of next week, on Monday, October 26, will indicate whether the weekend decline was merely a technical correction or the start of a longer downturn. Key factors to watch include whether certified inventories at ICE increase as expected from the volume of bags awaiting grading, whether the Brazilian real maintains its upward momentum, whether harvest progress in Brazil and the Central Highlands pushes more supply onto the market, and whether domestic prices can hold the VND 90,000/kg threshold.
For farmers currently in the harvest season, the current decline is not a basis for panic-selling the entire output, but it is also not a signal to hold stock waiting for higher prices without a plan. A prudent approach is to sell a portion to rotate capital, retain high-quality stock, and monitor reference prices and harvest progress before making further decisions.
6. Coffee market outlook for October 25, 2026
The final session of the week closed a week of declining trading on both international exchanges and the domestic market. London Robusta fell for the fourth consecutive session, New York Arabica reversed direction after a recovery, Robusta inventories rose to a 13-month high while Arabica inventories fell to a five-week low but remained under pressure from expectations of a rebound in stocks. Domestically, the average unhulled coffee price across four regions retreated from VND 91,700/kg on October 22 to VND 90,700/kg on October 24, approaching the VND 90,000/kg mark.
The short-term trend still leans bearish, but the milder decline in Arabica compared to Robusta indicates the market has not entered a state of widespread panic selling. A single up or down session at the start of next week is insufficient to confirm a long-term trend. Coffee growers, dealers, and export businesses should combine reference prices with commodity quality, delivery demand, and actual costs before making buying or selling decisions.
References
- Vietnam.vn, Coffee prices today 24/10: Continued decline despite ICE inventories at a 5-week low, citing Barchart analysis on profit-taking pressure and Arabica inventories at ICE. https://www.vietnam.vn/en/gia-ca-phe-hom-nay-24-10-tiep-tuc-giam-du-ton-kho-ice-thap-nhat-5-tuan
- Vietnam.vn, Agricultural commodity prices today 24/10/2026: Coffee prices plummeted over the weekend, Robusta inventories at ICE rose to 6,612 lots, the highest in 13 months, and the strengthening Brazilian real supported Arabica. https://www.vietnam.vn/en/gia-nong-san-hom-nay-24-10-2026-gia-ca-phe-lao-doc-cuoi-tuan-gia-tieu-co-the-phuc-hoi-vao-cuoi-nam-gia-dau-bat-tang-3-len-dinh-gan-6-thang
- Vietnam.vn, Agricultural commodity news today 24/10: Coffee prices continued to fall, domestic prices in four regions on 24/10 and the closing levels of the previous session for various contract months. https://www.vietnam.vn/en/ban-tin-nong-san-hom-nay-24-10-gia-ca-phe-tiep-tuc-giam
- Vietnam.vn, Coffee prices today 24/10/2026 tracking London and New York sessions: Domestic prices on 23/10 and trading prices during the session on 23/10. https://www.vietnam.vn/en/gia-ca-phe-hom-nay-24-10-2026-theo-doi-phien-london-new-york
- SAVINA Coffee Knowledge, Coffee market analysis for 22/10/2026: Closing levels and domestic price table for 22/10. https://caphesachvietnam.com/phan-tich-thi-truong-ca-phe-2026-10-22
- Note on data: The price report on 23/10 recorded some intraday prices, such as November Robusta at USD 3,322/ton and December Arabica at 313.95 US cents/pound, which differed from the closing prices. This article uses only closing prices, as the closing prices are consistent across all four contract months when calculating session-to-session changes, whereas intraday recorded prices do not align in this manner.
SAVINA Coffee Knowledge continues to update coffee knowledge and market developments, supporting readers in tracking prices and better understanding the factors affecting the coffee industry. Read more coffee knowledge at the SAVINA Coffee Knowledge Library.